FOR INDEPENDENT HOTEL & MOTEL OWNERS • LIVE AT CACTUSCAPITALHQ.COM
See what a lender will see, before you apply
CactusCapital is an evidence-first business-funding marketplace for independent hotel and motel owners. It turns your bank, accounting and operating data into a verified loan file a lender can actually use, shares it only with the lenders you choose, and puts every offer on one schedule.
Owners never pay. No advance fees, ever. The walkthrough uses a synthetic sample hotel, so you can explore it before signing up.
3
Separate assessments: funding readiness, repayment risk and provider fit, never blended into one grade
1
Schedule and one APR method for every offer, including a daily-debit merchant cash advance
0
Advance fees. Owners never pay, ever
SBA FOIA
Public SBA 7(a) and 504 hotel lending data, built from the SBA’s FOIA files
Three answers, never one grade
Too many owners end up on daily-debit advances because their file is not lender-ready, not because their hotel cannot carry a loan. CactusCapital answers the three questions a lender asks, separately and with the rule behind every number.
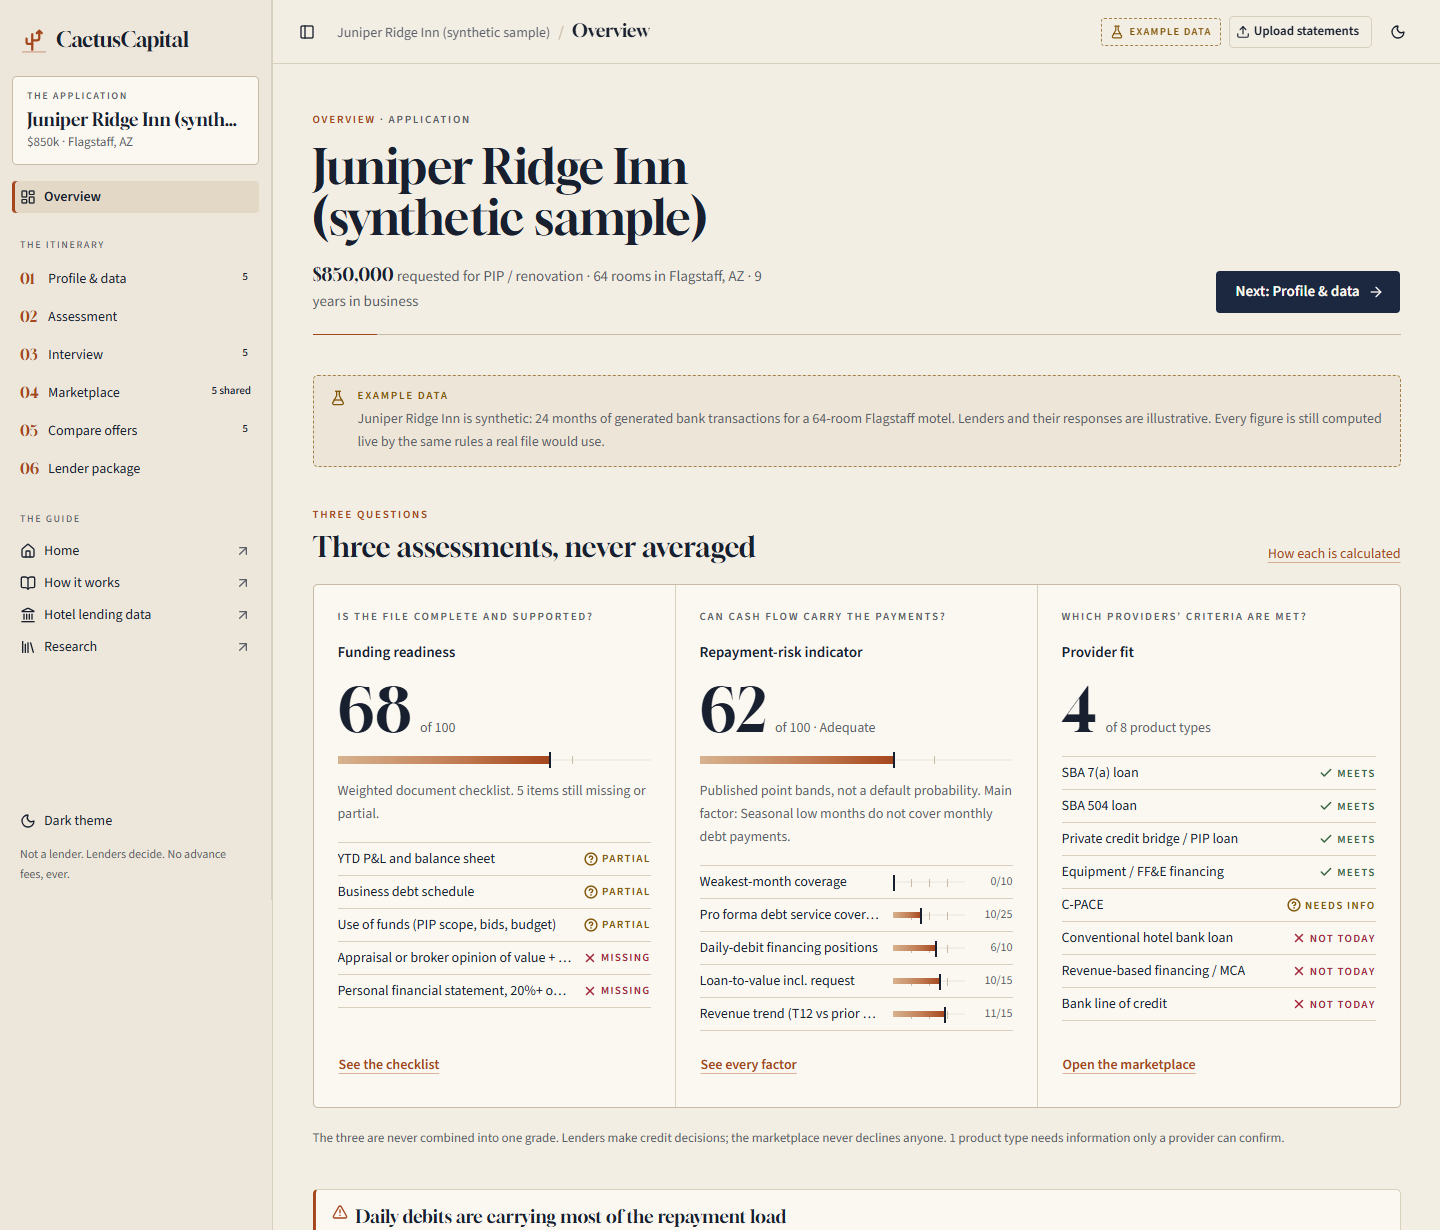
Synthetic sample hotel: Juniper Ridge Inn, 64 rooms, Flagstaff
Is the file complete and supported?
Funding readiness
68 of 100
A weighted document checklist. In the sample, 5 items are still missing or partial.
Can cash flow carry the payments?
Repayment-risk indicator
62 of 100 · Adequate
Published point bands for DSCR, trend, liquidity, daily debits and more. Not a predictive credit score.
Whose published criteria are met?
Provider fit
4 of 8 product types
Meets Needs info Not today
Pass, fail or unknown against each product’s published criteria: SBA 7(a), SBA 504, PIP bridge, equipment, C-PACE…
Three answers, never one grade. The three are never averaged. Lenders make the credit decisions.
How it works for owners
Six steps, in order, from raw statements to a package a lender can underwrite. You can stop at any step, and nothing reaches a lender until you share it.
-
1Profile & data
Bank, accounting and operating data become a verified file.
-
2Assessment
Readiness, repayment risk and provider fit, each on its own.
-
3Lender questions
Answer what an underwriter would ask, before they ask it.
-
4Share by consent
Pick the lender categories. Nothing goes anywhere else.
-
5Compare offers
Every offer on one schedule with an estimated APR.
-
6Lender package
Memo PDF, financials Excel and the consent record.
Verified, not typed in
Built from your own data
Bank, accounting and operating data become the file. Gaps and unusual items are flagged so you can fix them before a lender sees them.
Rules you can read
Every number has a rule
Readiness is a weighted checklist. Repayment risk uses published point bands. Provider fit is pass, fail or unknown against each product’s published criteria.
Your file, your call
Shared only by consent
You choose the lender categories that may see the file, and you can withdraw consent at any time.
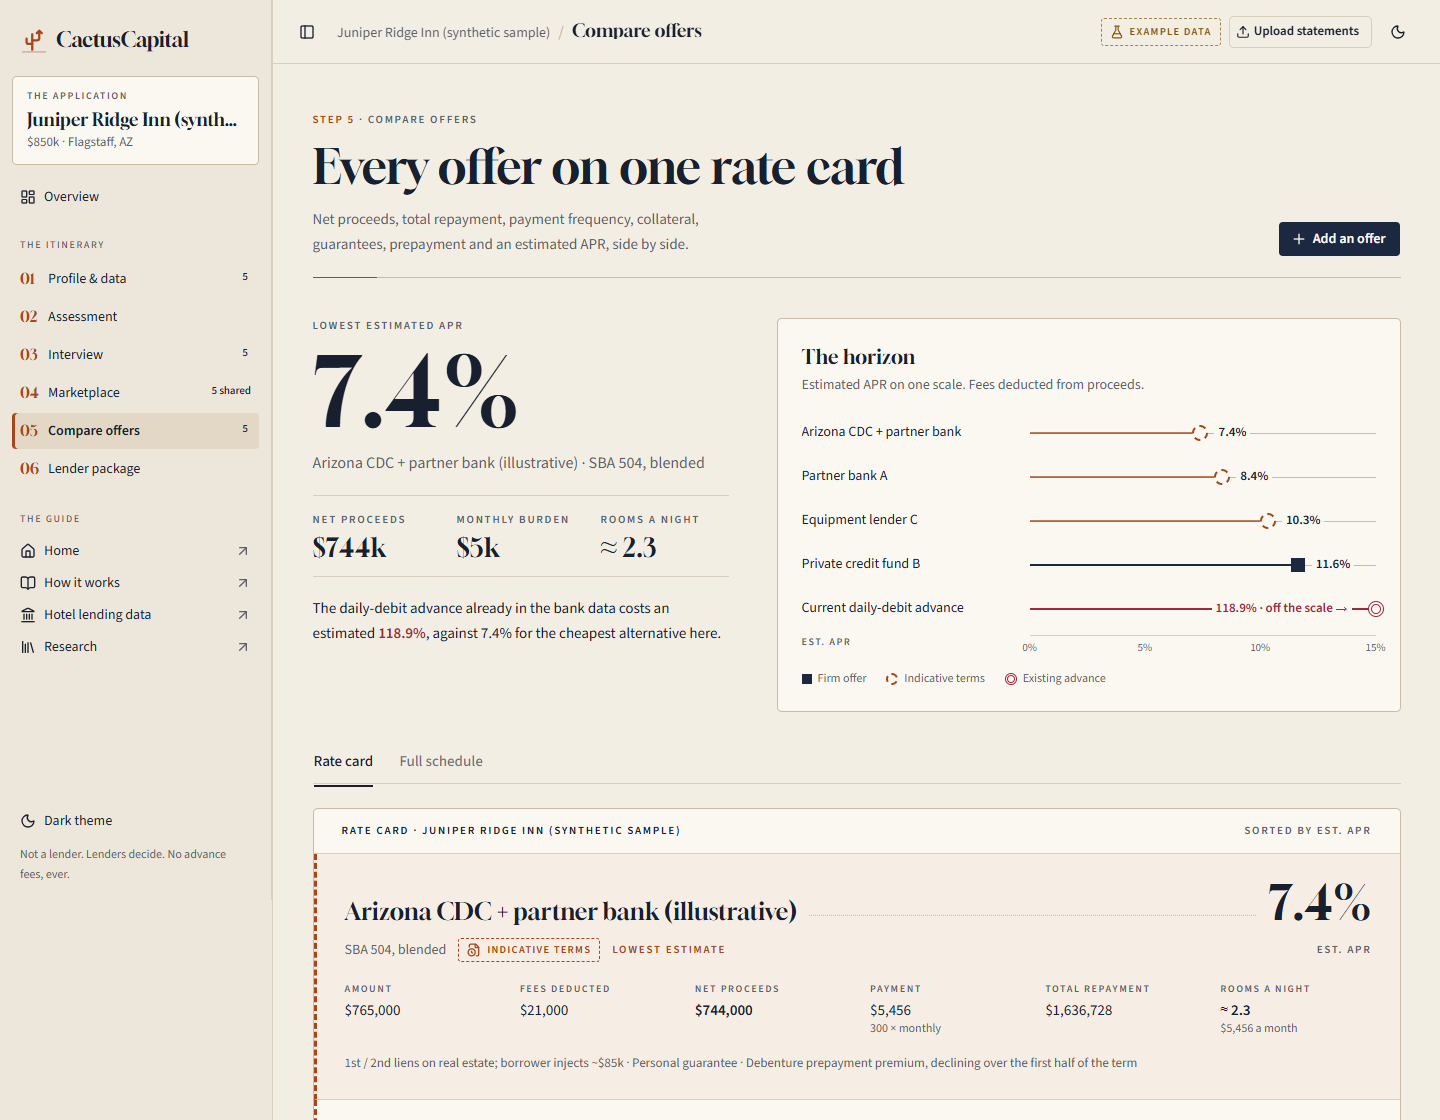
Every offer on one schedule
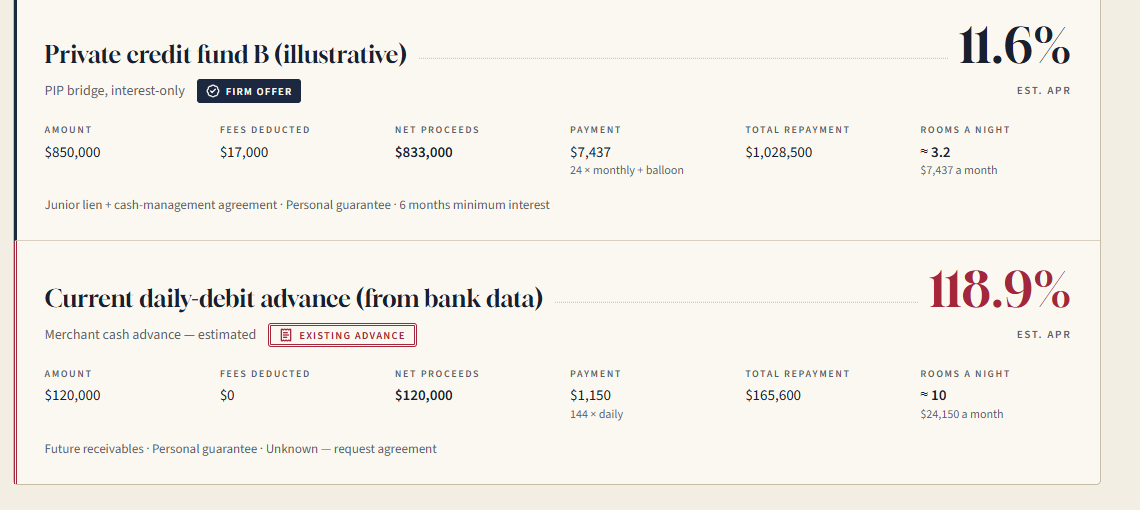
Net proceeds, total repayment, payment frequency, collateral and an estimated APR, side by side. A daily-debit advance goes on the same schedule as an SBA loan, so the comparison is honest. Rooms a night, the monthly payment restated in nightly room takings, sits next to every est. APR.
Synthetic sample hotel: Juniper Ridge Inn, 64 rooms, Flagstaff
What the advance really costs
Estimated APR on one scale (0–120%), with the monthly payment restated as rooms a night beside it.
Offers shared with lenders (illustrative)Existing daily-debit advance
7.4% est. APR · ≈ 2.3 rooms a night
8.4% est. APR · ≈ 2.8 rooms a night
10.3% est. APR · ≈ 2.7 rooms a night
11.6% est. APR · ≈ 3.2 rooms a night
118.9% est. APR · ≈ 10 rooms a night
How it works for lenders
Lenders get a file they can underwrite instead of a stack of statements, and they make every credit decision.
Lender package
Memo, financials, consent
A branded package: a memo PDF, the financials in Excel and the owner’s consent record, with every figure traced to its rule.
Provider fit
Criteria checked up front
Each product is checked as pass, fail or unknown against its published criteria, so a lender sees what is known and what still needs confirming.
Market context
Public SBA hotel data
The public data page summarises SBA 7(a) and 504 hotel lending from the SBA’s FOIA files, so owners and lenders start from the same facts.
Independent hotel and motel owners
Free, always
- A verified loan file built from your own bank, accounting and operating data
- Three separate assessments, so you see what a lender will see
- You choose who sees the file, and can withdraw consent
- Every offer, including an advance, on one schedule
- No advance fees, ever
Lenders
Verified packages
- A branded lender package: memo PDF, financials Excel and the consent record
- Every figure traced to the rule that produced it
- Provider fit against each product’s published criteria
- Team access through your organization
- You make every credit decision
Consent first, and honest about what it is
Nothing reaches a lender unless the owner shares it with that lender category, and the owner can withdraw it.
Step 1
The owner builds the file
Bank, accounting and operating data become a verified file. Nothing reaches a lender at this stage.
Step 2
The owner chooses lender categories
Sharing is per category, for example:
SBA 7(a)SBA 504PIP bridgeEquipmentC-PACE
Step 3
Those lenders see the package
Only lenders in the chosen categories can open it, with the consent record attached.
Not a lender
Lenders decide
CactusCapital is not a lender and makes no credit decisions; lenders decide. The marketplace never declines anyone.
Owners never pay
No advance fees, ever
Owners never pay. No advance fees, ever.
Estimates are not offers
Labelled as estimates
Est. APR and rooms a night are estimates for comparison. Estimates are not offers.
Not a credit score
Published point bands
The repayment-risk indicator uses published point bands. It is not a predictive credit score.
See your hotel the way a lender will
Walk through the synthetic sample hotel first, or start your own file. Owners never pay.
Boniface Osonwanne, CEO • Bon@Osonwanne.com • 602-632-9589 • cactuscapitalhq.com • More ventures: see Ventures
CactusCapital is a venture of Osonwanne Group LLC. CactusCapital is not a lender and makes no credit decisions; lenders decide. Owners never pay. No advance fees, ever. Estimates are not offers. The repayment-risk indicator uses published point bands and is not a predictive credit score. The public walkthrough uses a synthetic sample hotel (Juniper Ridge Inn, 64 rooms, Flagstaff); its lenders, offers and responses are illustrative.